Choosing the right car insurance means deciding what protection you need first, then comparing policies with equivalent limits and deductibles. The lowest premium is not automatically the right choice if it buys less protection, carries a deductible you could not comfortably pay, or comes from an insurer you have not checked.
Quick Take
Start with your state’s requirements and any lender or lease conditions, decide which losses you want the policy to protect you against, choose deductibles you could realistically pay, and then compare like-for-like quotes. Before buying, check the insurer’s licensing, complaint, and financial information and review the issued policy for accuracy.
This guide focuses on personal auto insurance in the United States. If you are shopping elsewhere, use information written for that jurisdiction; a UK car insurance comparison service, for example, uses coverage categories that should not be treated as a guide to U.S. state requirements.
Start With the Coverage You Actually Need
Before comparing premiums, determine what the policy needs to cover. The National Association of Insurance Commissioners explains that each state sets its own auto insurance rules, although most require drivers to carry at least a basic level of coverage. Other requirements vary by state.
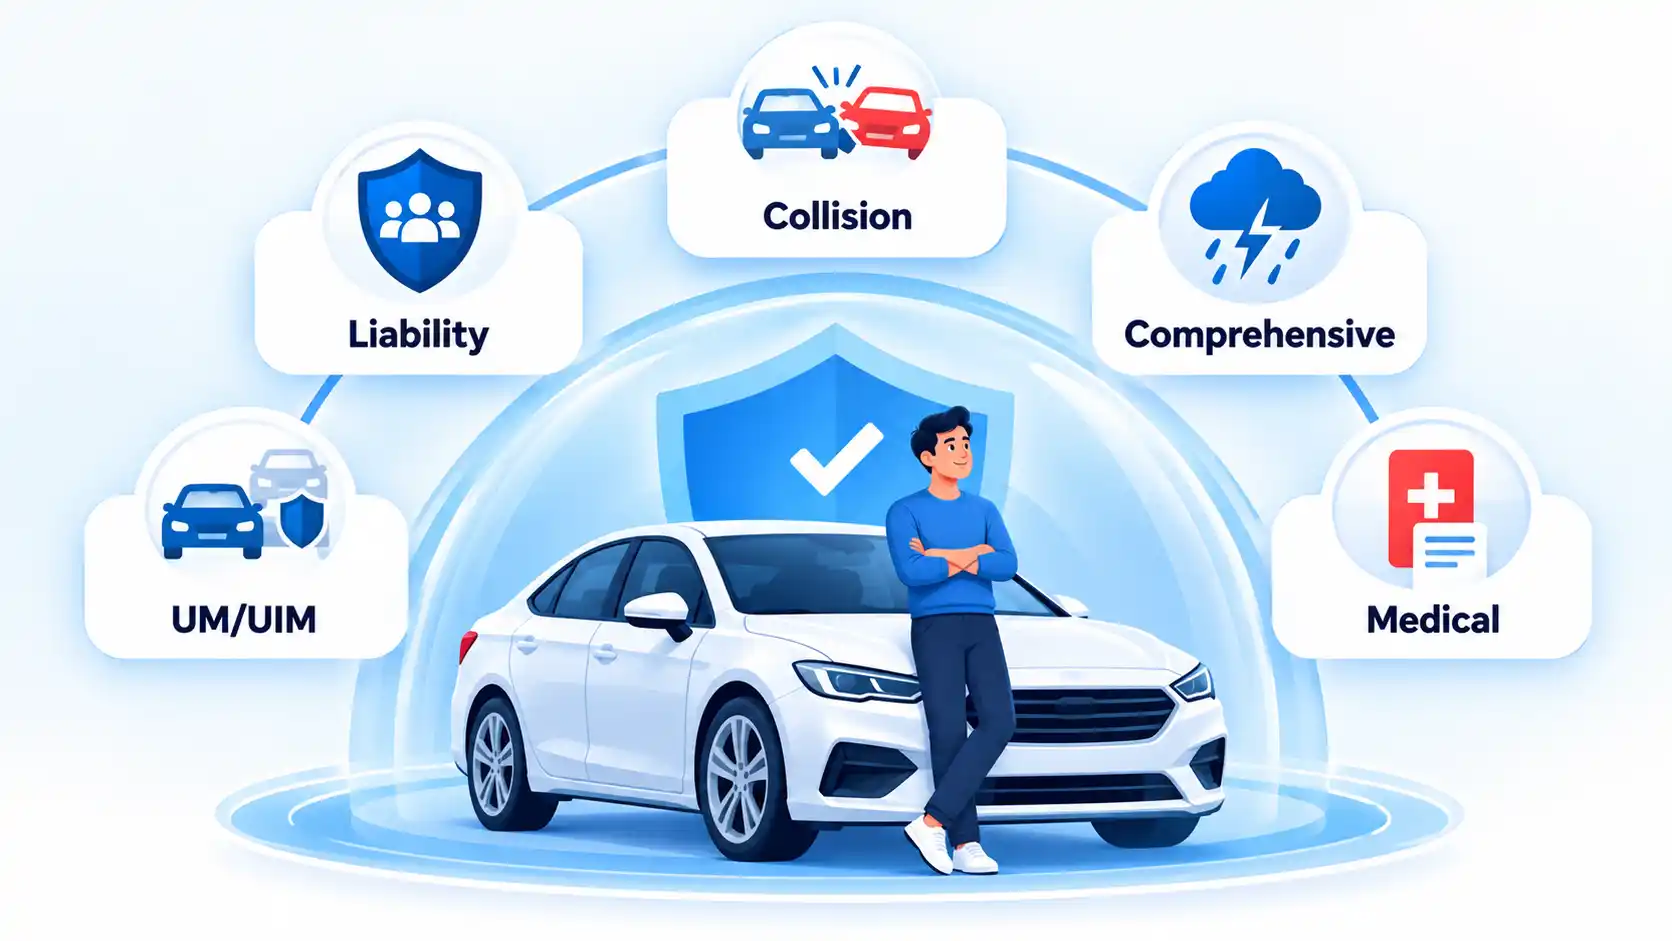
Liability coverage protects against certain injuries or property damage you cause to others. Bodily injury liability applies to covered injuries, while property damage liability applies to damage to another person’s vehicle or property. A state-required minimum is a legal baseline, not a guarantee that every possible loss will fit inside that limit.
Uninsured motorist and underinsured motorist coverage can provide protection when an at-fault driver has no insurance or insufficient insurance. Medical payments coverage and personal injury protection, commonly shortened to PIP, may also be required or available depending on where you live.
Collision and comprehensive protect your own vehicle in different circumstances. NAIC’s 2026 explanation of auto insurance coverage describes collision as protection for vehicle damage caused by a collision with another vehicle or object, while comprehensive covers specified non-collision events such as theft, fire, hail, windstorm, flood, or impact with an animal. Collision and comprehensive generally are not required by state law, although lenders may require them for financed or leased vehicles.
That distinction matters because two policies with the same premium can protect you very differently. A cheaper policy may have lower liability limits, omit physical-damage coverage, or carry larger deductibles. If you need more detail on liability limits and financial exposure, how much car insurance you need depends on more than simply meeting the legal minimum.
Choose Limits Based on the Loss You Need to Absorb
A coverage limit is the maximum amount the policy will pay for a covered loss, subject to the policy terms and the particular limit involved. Legal minimums establish required protection, but they do not guarantee that the limit will be enough for a serious claim.
The Insurance Information Institute explains that accident costs can exceed minimum liability limits. If you are legally responsible for costs above what the policy covers, you may have to pay the remaining amount yourself.
There is no single liability limit that is appropriate for every driver. The practical question is how much financial exposure you want the insurer to assume and how much risk you could absorb yourself. Available limits, state rules, household finances, assets, and other personal circumstances can affect that decision.
For physical damage to your own vehicle, the decision is different. Collision and comprehensive coverage generally respond to covered losses involving the insured vehicle rather than providing an unlimited replacement benefit. For an older vehicle, compare its value and likely repair or replacement cost with the premiums and deductibles involved, while also checking whether a lender still requires the coverage.
The difference between collision and comprehensive car insurance becomes especially important when deciding which types of damage you are willing to pay for yourself.
Pick a Deductible You Could Actually Pay
A deductible is the amount you pay toward a covered loss before the insurer pays its share under the applicable coverage. Collision and comprehensive commonly have deductibles, and a higher deductible can reduce the premium because you are retaining more of the financial risk.
That does not mean the largest available deductible is automatically the better choice. If you are comparing a $500 deductible with a $1,000 deductible, the higher option means you would need to absorb an additional $500 after a covered loss before the insurer’s payment is calculated under that coverage. The Insurance Information Institute identifies $500 and $1,000 as common deductible examples and notes the general relationship between higher deductibles and lower premiums.
Connect the deductible to money you could realistically access after an accident, theft, or other covered event. A lower premium is of limited value if the deductible would create a financial problem when you need to make a claim.
Compare Quotes on the Same Basis
Once you know which coverage types, limits, and deductibles you want, compare quotes using those same inputs. Otherwise, an apparent price difference may simply be a difference in how much insurance each quote provides.
The Insurance Information Institute recommends comparing the same types and amounts of coverage. For example, a policy with $50,000 of property damage liability is not directly comparable with one providing $100,000 if you are trying to determine which insurer charges less for equivalent protection.
Once the coverage inputs are fixed, you can request quotes directly from insurers, work through an agent, or use a service to compare car insurance quotes. Regardless of the shopping route, compare the resulting policies using the same limits, deductibles, drivers, vehicles, and intended use.
The table below shows which details should be aligned before you treat two premiums as directly comparable.
| Quote element | What to match | Why it matters |
|---|---|---|
| Liability limits | Use the same bodily injury and property damage limits. | Lower limits can make one quote appear cheaper while leaving more financial exposure outside the policy. |
| Collision and comprehensive | Include or exclude the same physical-damage coverages. | A policy that does not protect your own vehicle is not equivalent to one that does. |
| Deductibles | Match collision and comprehensive deductibles. | A higher deductible transfers more of a covered loss to you and can reduce the premium. |
| Drivers and vehicles | Use the same drivers, vehicles, garaging details, mileage, and vehicle use. | These details can affect how the insurer evaluates and prices the risk. |
| Optional benefits | Check items such as rental reimbursement and glass coverage separately. | Additional benefits can change both the premium and what the policy provides after a loss. |
Do not use another driver’s premium as proof of what you should pay. NAIC identifies rating factors including location, driving experience and record, claims history, vehicle type and use, miles driven, selected coverages, and deductibles. Credit information may also be used where applicable under state rules. Different driver and vehicle profiles can therefore produce different prices from the same insurer.
Check the Insurance Company, Not Just the Price
A low quote is only one part of the decision. Before buying, identify the legal name of the company issuing the policy and confirm that it is licensed where you live.
The NAIC consumer resources provide access to Consumer Insurance Search, which includes information about insurance-company complaints, licenses, and financial health. NAIC also advises consumers to check the exact company name because an insurer may operate through differently named subsidiaries.
Complaint information needs context. NAIC advises against choosing an insurer from one factor alone and recommends considering complaints alongside financial information and business volume. A raw complaint total therefore should not be treated as a stand-alone verdict on an insurer.
You can also consider service characteristics that affect how you prefer to manage a policy, such as available claims-reporting methods, access to agents, and online account tools. These factors can help distinguish policies once the coverage, deductibles, and insurer checks already meet your requirements.
Look at Discounts and Optional Features After the Core Coverage
Discounts can reduce the final price, but they should be considered after you establish the coverage you need. Ask each insurer which discounts apply to the quote you are actually considering rather than assuming an advertised discount will apply to you.
For example, NAIC notes that some insurers offer discounts when home and auto insurance are purchased together. Eligibility, available programs, and the resulting price vary, so compare the final premium and coverage rather than the advertised discount by itself.
If GEICO is among the companies you are already comparing, commercial pages describing GEICO car insurance discounts can identify discount categories to ask about, but verify actual eligibility, availability, and policy terms with the insurer before treating a discount as applicable to your quote.
Usage-based insurance is another case where price and features need to be considered together. NAIC guidance on usage-based insurance explains that insurers may use driving information to help determine premiums and advises consumers to understand what data is collected. This makes privacy and data collection part of the decision as well as potential price changes.
A deeper comparison of usage-based car insurance should therefore consider monitoring practices as well as possible savings.
Review the Final Policy Before You Rely on It
A quote shows proposed terms. The issued policy and declarations or information page show the details of the coverage you actually purchased, so review them rather than assuming every detail matches what you expected.
Verify the result
- Your name, address, listed drivers, and vehicle information are accurate.
- The liability and other coverage limits match what you selected.
- Collision and comprehensive appear when you intended to buy them, and their deductibles are correct.
- Any discounts included in the final premium are shown correctly.
- The effective date starts when you need coverage, with no unintended gap between policies.
These checks are consistent with long-standing NAIC guidance on reviewing auto policy information, including addresses, vehicle details, drivers, coverages, limits, deductibles, dates, and discounts. If something differs from what you requested, ask the insurer or agent to explain or correct it before relying on the document.
A Simple Way to Make the Final Choice
Once you have comparable quotes, narrow them in this order so that price does not eliminate necessary protection before you evaluate the rest of the policy.
- Remove policies that do not meet your coverage requirements. Check state requirements and any lender or lease conditions first, then remove options that do not provide the protection you decided you need.
- Remove deductibles you could not realistically pay. Do not choose a higher deductible solely for a lower premium if paying that deductible after a covered loss would create a financial problem.
- Compare the remaining quotes on equivalent terms. Match limits, deductibles, drivers, vehicles, and relevant optional benefits before judging the premium difference.
- Check the insurer behind each serious option. Confirm licensing and review available complaint and financial information using regulator resources.
- Use price and service features to make the final distinction. Once the remaining policies meet your coverage and insurer requirements, compare their final premiums, applicable discounts, service options, and other features that matter to you.
The right car insurance is therefore not simply the policy with the smallest premium or the longest list of advertised discounts. It is one that meets applicable requirements, covers the losses you have decided not to absorb yourself, uses limits and deductibles you understand, and remains competitive when compared with genuinely equivalent alternatives.
