High-risk payment processing can let a business accept cards when ordinary merchant-account options are limited, but approval is only part of the decision. Before you sign, check whether the processor supports your real business model, how reserves and settlement affect cash flow, what can put the account at risk, and which security and compliance duties still belong to you.
Quick Take
Do not judge a high-risk processing offer by the advertised transaction rate alone. Confirm that your actual products and sales model are approved, then review reserves, settlement timing, account limits, dispute expectations, security responsibilities, and termination terms in writing.
What High-Risk Payment Processing Actually Means
A business is generally treated as high risk when the bank or payment company taking responsibility for its card transactions sees a greater chance of fraud, disputes, financial loss, compliance problems, or other account risk. The label is not limited to one industry, and different processors can make different underwriting decisions about the same business.
The financial institution that has the direct merchant relationship is called an acquirer, or acquiring bank. Before a merchant begins accepting Visa payments, the acquirer must perform compliance checks as part of onboarding. Acquirers can also use Visa’s merchant screening service before making an onboarding decision to identify merchants or related agents associated with elevated risk or prior termination records.
Some legal business categories can receive closer scrutiny because the payment network considers them more exposed to illegal activity or other risk. Visa states that acquirers supporting certain higher-risk categories must apply enhanced safeguards and closer monitoring. That does not mean every merchant in such a category is doing something wrong. It means the processor or acquirer may require more information, stronger controls, or different account terms.
A merchant account is the arrangement that allows a business to receive card-payment proceeds through the acquiring side of the payment system. A payment processor handles parts of the transaction flow, while a gateway usually provides the technical connection that passes payment information between the checkout and processing systems. Understanding the difference between a payment gateway, processor, and merchant account makes it easier to see which company is responsible for each part of your setup.
Confirm the Processor Supports Your Business Model
A provider saying that it works with “high-risk businesses” is not enough. Your actual products, services, sales method, countries, currencies, average transaction size, expected volume, and recurring-payment model can all affect whether an account is approved and how it is monitored.
For example, an online store selling one-time physical products does not have the same operating profile as a subscription service collecting recurring payments or a travel business taking money long before the service is delivered. The processor needs an accurate picture of what customers buy and when the business fulfills its obligations.
Some merchants use a specialist high-risk payment processing provider when their business category falls outside a mainstream processor’s risk appetite, but the merchant agreement still needs to reflect the products, markets, limits, and account terms the business will actually use.
Do not hide or soften important details simply to improve the chance of approval. Acquirers are expected to screen prospective merchants before onboarding, and Visa’s merchant due-diligence system supports those onboarding checks. An account obtained using inaccurate information can create a larger problem later if the processor discovers that the business differs materially from what was approved.
Before signing, compare the application, approval notice, and merchant agreement with the business you actually operate. If a major product category, website, sales channel, country, transaction profile, or recurring-payment model is missing or described incorrectly, get the discrepancy resolved in writing first.
Read the Full Cost, Reserve, and Settlement Terms
The quoted processing rate tells you only part of what an account can cost. High-risk arrangements can also affect when you receive money and how much of each payout remains temporarily unavailable.
A reserve is money held back to cover possible future refunds, disputes, or other losses. The exact structure depends on the provider and account. Stripe, for example, defines its reserve as a temporary hold on part of a business’s funds and states that the amount depends on the risk associated with the business. That is an example of how one processor handles reserves, not a universal formula for every merchant account.
A reserve can affect working capital even when the processing fee itself looks reasonable. A business that needs today’s sales revenue to pay suppliers next week may feel a reserve much more strongly than a business with a large cash buffer. Understanding how a reserve hold affects cash flow is therefore part of evaluating the real cost of an offer.
The same principle applies to settlement. Settlement timing is the period between successful transactions and the point when usable funds reach you. Longer settlement periods, reserve holds, or account limits can matter more to day-to-day operations than a small difference in the advertised transaction rate.
| Term | What to identify | Why it matters |
|---|---|---|
| Processing charges | Transaction, recurring, gateway, account, dispute, and other applicable fees | Shows the cost beyond the headline percentage |
| Reserve | How much can be held, how the hold works, and when funds are released | Determines how much sales revenue may be temporarily unavailable |
| Settlement | When processed funds normally become available for payout | Affects working capital and payment planning |
| Account limits | Transaction, volume, country, currency, product, or other operating restrictions | Unexpected limits can interrupt otherwise legitimate sales |
| Exit terms | Termination, amendment, notice, and post-termination fund conditions | Shows what can happen to the account and remaining funds if the relationship ends |
Ask how each material charge or restriction is triggered rather than assuming a label means the same thing across providers. If the sales representative’s explanation conflicts with the contract, resolve the difference before treating the offer as final.
Know the Rules That Can Put Your Account at Risk
Merchant-account risk does not end once processing begins. Card networks and acquirers continue to monitor activity, especially when fraud, disputes, prohibited activity, or unusual transaction patterns suggest that an account may require closer review.
Visa’s current Visa Acquirer Monitoring Program monitors fraud and dispute performance at both acquirer and merchant level. The program is designed to identify significant problems rather than ordinary business fluctuations, so excessive fraud or disputes can become more than a customer-service issue.
Mastercard also maintains merchant-related compliance programs covering business risk, excessive chargebacks, fraud, and merchant auditing. The exact rules and thresholds can change, so a merchant should not depend on an old percentage copied from a blog post or previous processor agreement.
Warning
Card-network programs and processor risk rules can change. Ask your processor or acquirer which current monitoring rules apply to your account instead of relying on a fixed chargeback or fraud threshold from an older source.
Account risk can also come from a mismatch between the business the acquirer approved and the business that later processes transactions. If you add a materially different product line, enter a new market, change the way customers are billed, or experience a sharp change in transaction volume, check whether the agreement requires notice or additional approval.
Reduce Fraud and Disputes Before They Escalate
A dispute happens when a cardholder challenges a transaction through their card issuer. Some disputes are connected to actual fraud, while others arise because a customer does not recognize the charge, expected a different product, could not cancel easily, or believes the merchant did not deliver what was promised.
That means fraud prevention and dispute prevention overlap but are not identical. Screening suspicious transactions can help with stolen-card activity, while clear billing descriptors, accurate product descriptions, realistic delivery expectations, accessible support, and clear refund or cancellation rules can reduce avoidable customer confusion.
Keep transaction and fulfillment records that make sense for your business. Depending on what you sell, useful evidence may include order details, customer communications, delivery records, service-access logs, cancellation requests, and refund records. The goal is not to collect unnecessary personal data. It is to retain the records genuinely needed to operate the service, respond to customer questions, and handle legitimate disputes.
Watch for sudden changes rather than focusing only on a single percentage. A rise in declined transactions, customer complaints, refunds, fraud alerts, or disputes can indicate a problem with marketing, checkout, fulfillment, billing, or fraud controls. If chargebacks put your merchant account at risk, the priority is to identify the underlying cause before the problem becomes routine.
If you accept Visa, ask your acquirer what your VAMP performance means for the account. The implications can depend on both merchant activity and the acquirer’s portfolio performance.
Keep Payment Data and Checkout Pages Secure
A secure payment gateway is useful, but it does not automatically make every part of your website secure. The merchant’s own website, third-party scripts, plugins, administrator accounts, and checkout implementation can still affect the safety of an online payment flow.
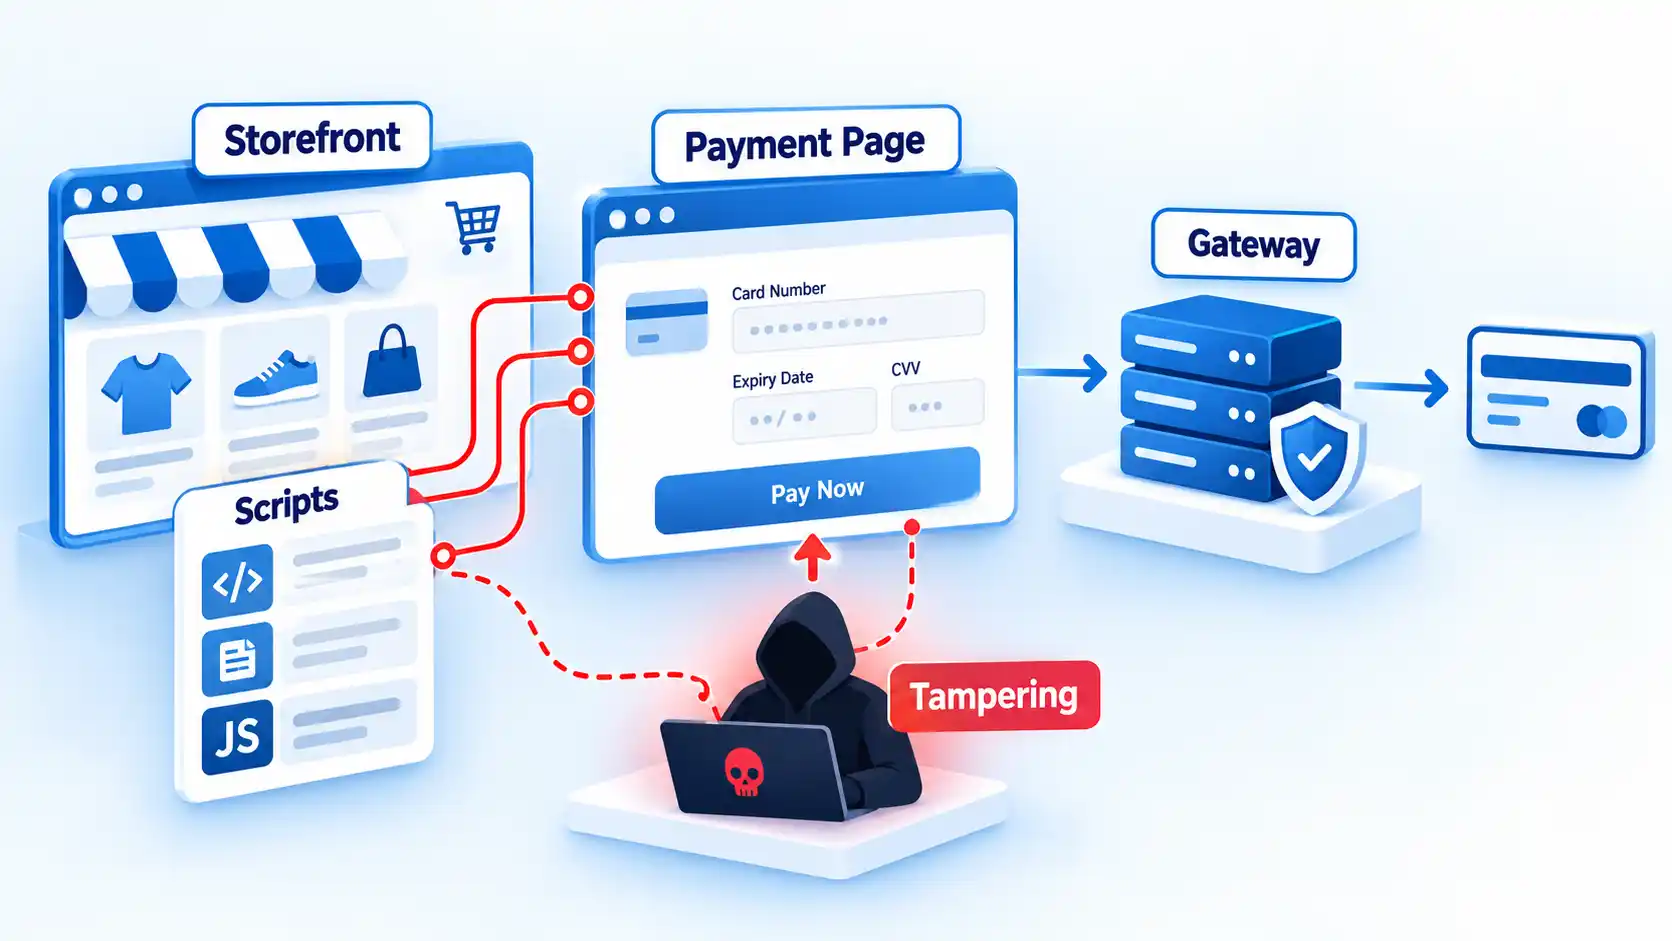
The Payment Card Industry Data Security Standard (PCI DSS) sets security requirements for organizations that handle payment-card data. For some e-commerce merchants using an embedded payment page from a third-party payment provider, current SAQ A eligibility includes confirming that the merchant webpage is not susceptible to script attacks that could affect the e-commerce system.
That particular criterion applies to an embedded third-party payment page or form. It does not apply in the same way when the merchant’s page redirects the customer to the payment provider’s site. Other SAQ A eligibility requirements still apply, so this distinction alone does not determine whether a merchant qualifies for SAQ A.
The distinction matters because “we do not store card numbers” is not the same as “nothing on our website can affect the checkout.” A malicious or compromised script on a merchant-controlled page can create a security issue even when another company supplies the embedded payment form.
Keep the payment environment as simple as practical, limit unnecessary access, maintain the systems and software that support checkout, and understand which party is responsible for each part of the implementation. PCI validation depends on the actual setup, so use current PCI SSC material and your payment provider’s instructions to determine which validation path applies to your business.
Payment security is also part of the broader job of protecting customer data. Collect only the information you genuinely need and limit access to people whose work requires it.
Put Customer-Facing Policies in Place Before Launch
Many payment disputes begin with an ordinary business problem rather than a sophisticated attack. A customer may not recognize the billing name, may misunderstand when a subscription renews, may expect a faster refund, or may believe a service should have been easier to cancel.
Before taking payments, make the important customer terms easy to find and consistent with what actually happens. Depending on the business, that can include pricing, renewal terms, cancellation rules, refund conditions, delivery or fulfillment times, trial conditions, and the name customers are likely to see on their card statement.
Consider a hypothetical subscription service that advertises a low introductory price but makes the renewal terms difficult to notice. Even if the original card payment was authorized, customers who later feel surprised by the renewal may contact their bank instead of the merchant. Clear terms and accessible support cannot eliminate disputes, but they remove preventable sources of confusion.
Do not assume one generic policy satisfies every legal or card-network requirement. Consumer-protection, subscription, gambling, financial-service, health-product, age-restricted, and other regulated categories can have different obligations depending on jurisdiction and business model. Where sector-specific rules apply, obtain qualified legal or compliance guidance rather than relying on a general payment-processing article.
What to Get in Writing Before You Sign
A sales conversation is useful for understanding an offer, but the written agreement is what you can refer back to when a question arises. Before committing, make sure the material terms you relied on are reflected in the application, approval, contract, or other binding account documents.
Verify the result
- Your approved products, services, websites, sales model, markets, and other material business details match what you actually operate.
- You know which provider, processor, acquirer, or other entity is responsible for the parts of the payment relationship that matter to your account.
- The written pricing identifies the transaction charges and any recurring, gateway, dispute, account, or other material fees that apply.
- Any reserve arrangement states how funds may be held and the conditions governing their release.
- You understand the normal settlement timetable and any conditions that can delay or change payouts.
- Transaction, volume, geographic, currency, product, or other account limits are clear enough for your expected operations.
- You understand how fraud, disputes, refunds, and chargebacks are handled and which responsibilities remain with your business.
- The agreement and technical setup make your gateway, PCI DSS, website-security, and customer-data responsibilities clear.
- You have reviewed amendment, termination, notice, and post-termination fund provisions rather than assuming the account will always continue unchanged.
- You know how to reach support or escalate an urgent problem involving payouts, fraud, disputes, security, or account restrictions.
If a material term is unclear, missing, or inconsistent with what you were told, resolve it before signing rather than assuming the most favorable interpretation. High-risk processing can be a workable payment solution, but the safest decision is one based on an accurate application, understandable cash-flow terms, realistic risk controls, and a written agreement that matches how your business will actually operate.
💬 Comments