A clear emergency savings goal is a specific dollar amount you can say out loud, and you reach it by looking back at your own unexpected expenses rather than borrowing a rule of thumb from the internet. The Consumer Financial Protection Bureau’s emergency fund guide says it directly: think about the most common kind of unexpected expenses you’ve had in the past and how much they cost, and that helps you set a goal for how much you want set aside.
That single instruction is the whole method. The rest of this guide supports it: why the fund deserves its own bucket, how to turn a vague “I should save more” into a number, and how to start putting money aside today even if the amount feels embarrassingly small.
Quick Take
Your target should come from receipts you’ve already paid, not from a generic formula. Once you have a defensible figure, the only thing that matters is making the first deposit and keeping the reserve walled off from everyday spending.
Why a Dedicated Fund Comes First
A financial shock doesn’t have to be dramatic to hurt. A fender bender, a broken appliance, a surprise medical bill, a damaged phone. The CFPB’s list of everyday emergencies is deliberately mundane, because that’s what actually derails a budget. The problem isn’t the size of the bill. It’s where the money comes from when there’s no reserve.
Without savings, the CFPB notes, even a minor shock can set you back, and if it turns into debt it can have a lasting impact. The chain usually runs like this:
- An unplanned expense lands with no dedicated money behind it.
- You cover it with a credit card or a loan, which can lead to debt that’s generally harder to pay off.
- Or you pull from other savings, like retirement funds, to make the bill go away.
The same CFPB guide points to research suggesting that people who struggle to recover from a financial shock have less savings to protect against the next one. That’s the argument for a dedicated fund in one sentence: it’s the buffer that keeps a bad week from becoming a long-term debt problem. Some readers facing existing debt also explore debt resolution programs as a separate path, but building a reserve is the preventive move that keeps you out of that situation in the first place.
Emergency Fund vs. General Savings
Here’s the distinction that makes the rest of this guide work. An emergency fund is a cash reserve specifically set aside for unplanned expenses or financial emergencies. It is not your general savings, and it is not part of your routine monthly expenses and spending.
| Question | Emergency fund | General savings |
|---|---|---|
| What it’s for | Unplanned expenses or financial emergencies | Planned goals and routine financial life |
| Typical examples | Car repairs, home repairs, medical bills, loss of income | Routine monthly expenses and spending |
| How it fits your budget | Kept separate from routine spending | Part of your normal monthly flow |
| When you draw on it | When an unplanned, non-routine bill hits | On your own schedule, for planned costs |
If your “emergency fund” is the same account you raid for groceries, a vacation, or a sale, it isn’t a reserve. It’s a checking account with a nicer name. The separation is the point.
What Makes a Savings Goal “Clear”
Most savings goals fail at the wording stage. “I want to save more” is a mood, not a goal. A clear goal has a number attached to it, and that number traces back to something real in your life.
Info
A goal is clear when you can state three things: the dollar amount, the specific past expenses that justify it, and the fact that the money is reserved for unplanned costs only. If you can’t name the expenses behind the number, the goal is still a guess.
Notice what’s missing from that definition: a universal multiple. The CFPB is explicit that the amount you need in an emergency savings fund depends on your situation. That’s not a hedge. It’s the actual instruction. A renter with an aging car and a high-deductible health plan faces a different expense profile than someone with stable housing and generous coverage. Your history is better data than someone else’s formula.
Step 1: Size Your Goal From Your Own Expense History
This is the core exercise. Work through it in one sitting and you’ll come out with a number you can actually defend.
- List the unexpected expenses you’ve actually had. Go back through the last year or two of bank and card statements and write down every unplanned bill: the car repair, the medical charge, the appliance that died, the phone you had to replace. Stick to expenses that were not part of your routine monthly spending.
- Write the real cost next to each one. Use what you actually paid, not an estimate. If you can’t find the exact figure, use the closest documented amount and mark it as approximate.
- Add them up and look at the pattern. The total gives you a defensible starting target. If one category dominates, say car repairs, that tells you where your risk concentrates and how much of the goal that category should cover.
- Set your goal amount and write it down. Commit to the summed figure as your target, or a rounded version of it. Record it somewhere you’ll see it, so the goal stops being abstract.
Verify the result
- You can state your goal as a specific dollar amount.
- You can name at least two real past expenses that justify that number.
- Your goal reflects your own situation rather than a borrowed rule of thumb.
Step 2: Start Building in Amounts You Can Sustain
The CFPB is direct about this: if you’re living paycheck to paycheck or don’t get paid the same amount each week or month, putting money aside can feel difficult, but even a small amount can provide some financial security. There are different strategies to build the fund, and the right one is the one you’ll keep doing.
- Move a first amount today, however small. The starting action is a transfer, not a plan. Put aside an amount you won’t miss this week and treat it as the first deposit against the goal you sized in Step 1.
- Pick a build strategy that matches your income pattern. If your pay is steady, a fixed recurring transfer is the simplest option. If your income is irregular, build around the weeks when money is available rather than committing to a rigid schedule you’ll break.
- Keep the fund separate from routine spending. The reserve only works if it isn’t sitting in the same pool you use for monthly expenses. Separate the money so a routine purchase can’t quietly consume it.
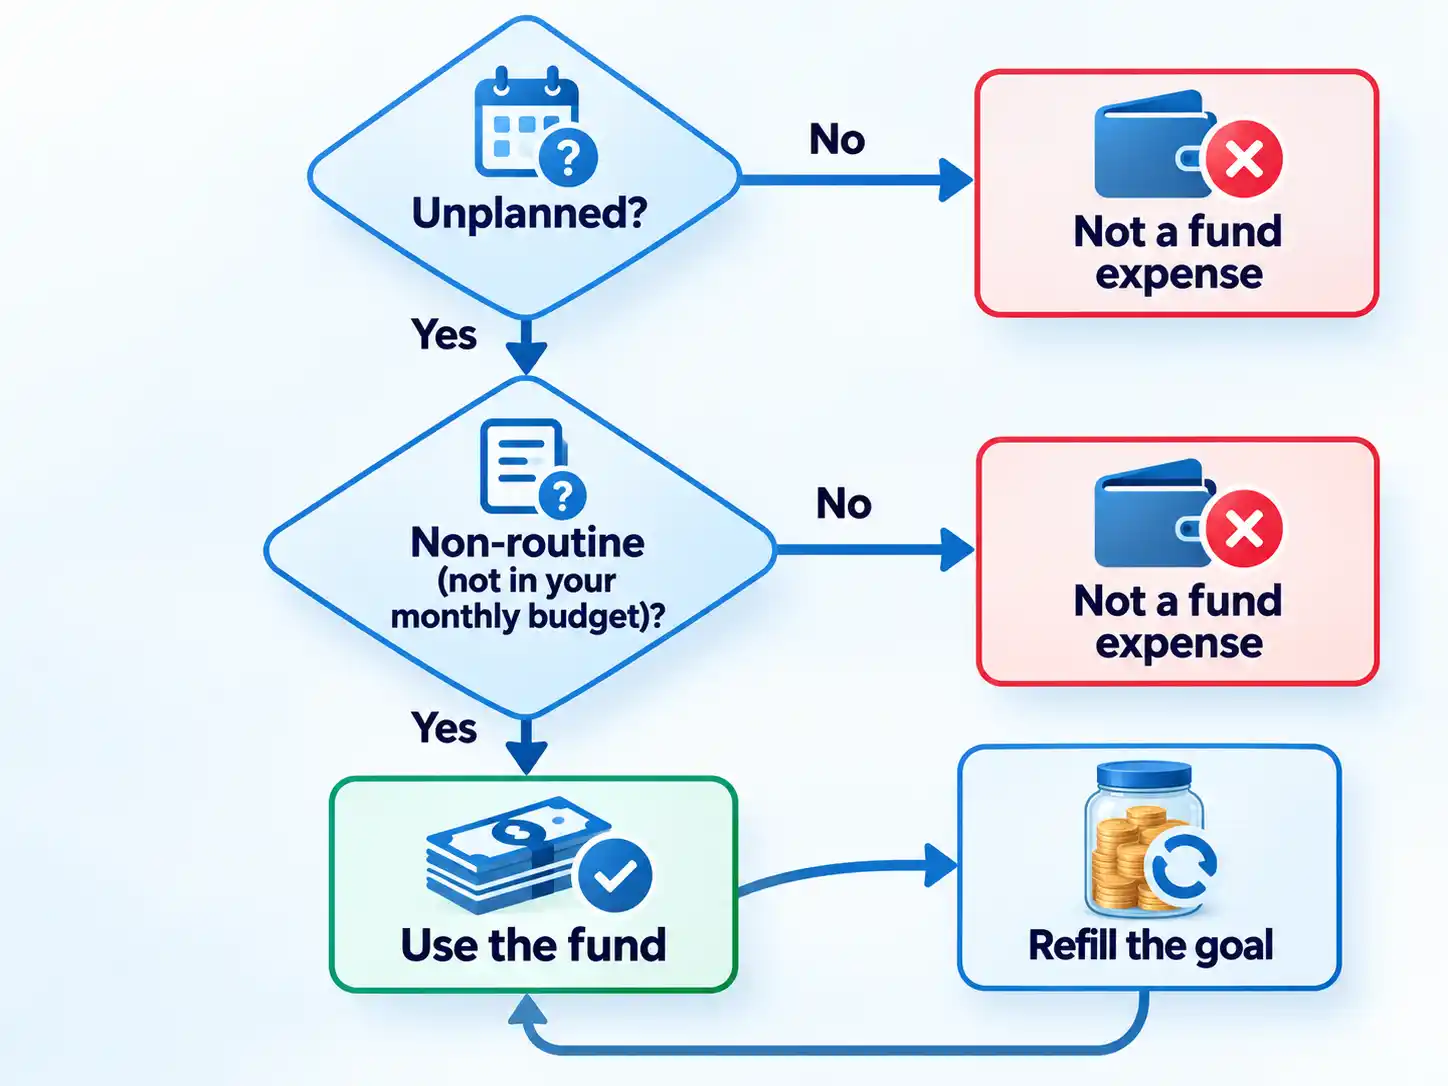
- Refill after you use it. When an unplanned expense draws the fund down, treat the next deposits as rebuilding the same goal, not as starting over.
When to Use It, and When Not To
The definition does most of the work here. Emergency savings are for large or small unplanned bills or payments that are not part of your routine monthly expenses and spending. That gives you a two-question test.
Success
Use the fund when the expense is both unplanned and non-routine: the car repair, the medical bill, the sudden loss of income. Leave the fund alone when the cost belongs in your normal monthly budget, even if paying it is annoying. A routine bill is a budgeting problem, not an emergency.
That boundary protects the reserve from the slow leak that kills most emergency funds: a series of “just this once” withdrawals for things that were predictable all along.
Common Ways Goals Stall
The two failure modes the CFPB names directly are the ones worth planning around. Everything else is usually a variation on them.
You’re living paycheck to paycheck and any amount feels pointless
The instinct is to wait until you can save “properly.” That’s backwards. The CFPB’s answer is that even a small amount can provide some financial security, so the first deposit matters more than its size. Start with an amount you can repeat, not an amount that impresses.
Your income is irregular, so a fixed savings schedule keeps breaking
If you don’t get paid the same amount each week or month, a rigid recurring transfer will fail the first slow month and you’ll abandon the goal. Build around the periods when money is actually available, and let the amount vary while the goal stays fixed.
You hit a real emergency and the fund is now empty
That’s the fund doing its job. It absorbed a shock that would otherwise have become credit card debt or a retirement withdrawal. Return to the same goal amount and start refilling. The target hasn’t changed; only your progress toward it has.
You keep dipping into the fund for non-emergencies
This usually means the money isn’t separated from routine spending. Revisit the boundary: if the expense was planned or routine, it doesn’t belong in the fund. Keeping the reserve distinct from your everyday money is what makes the rule enforceable.
A Note on Scope
Warning
This guide is a starting method, not a guaranteed outcome and not individualized financial advice. It won’t tell you which account or institution to use, because that decision depends on details this method doesn’t cover. Use it to define and begin building a goal, and treat the specific product choice as a separate question.
That’s a deliberate boundary, not an oversight. The sizing and building method is the part you can act on today with confidence. Where the money physically lives is a different decision with its own trade-offs, and it deserves its own research rather than a rushed recommendation here.
The Bottom Line
A clear emergency savings goal comes from your own receipts, not from a formula someone else wrote. List your past unexpected expenses, total what they cost, commit to that number, and move a first amount today, even a small one. Keep the fund separate from routine spending, use it only for unplanned and non-routine costs, and refill it when it does its job.
That’s the entire method, and it’s executable this afternoon. The goal you can name and defend beats the goal you borrowed and never started.
Key Takeaways
- Size your goal from your own past unexpected expenses and their real costs, not a universal multiple.
- An emergency fund is a cash reserve for unplanned expenses, kept separate from routine monthly spending.
- Start with an amount you can sustain. A small reserve still provides financial security.
- Use the fund only for expenses that are both unplanned and non-routine, then refill it.
- This is a starting method, not individualized financial advice or a product recommendation.

💬 Comments